Daniel accepted a job offer with a modest base salary and a stock option grant he barely glanced at during negotiations, assuming it was mostly a recruiting formality. Four years later, after the company went public, that overlooked grant turned out to be worth more than his entire base salary paid over the same period, but only because he happened to exercise the options at the right time rather than letting them expire unexercised, something a coworker in the next cubicle failed to do with an equally valuable grant.
What Employee Stock Options Represent
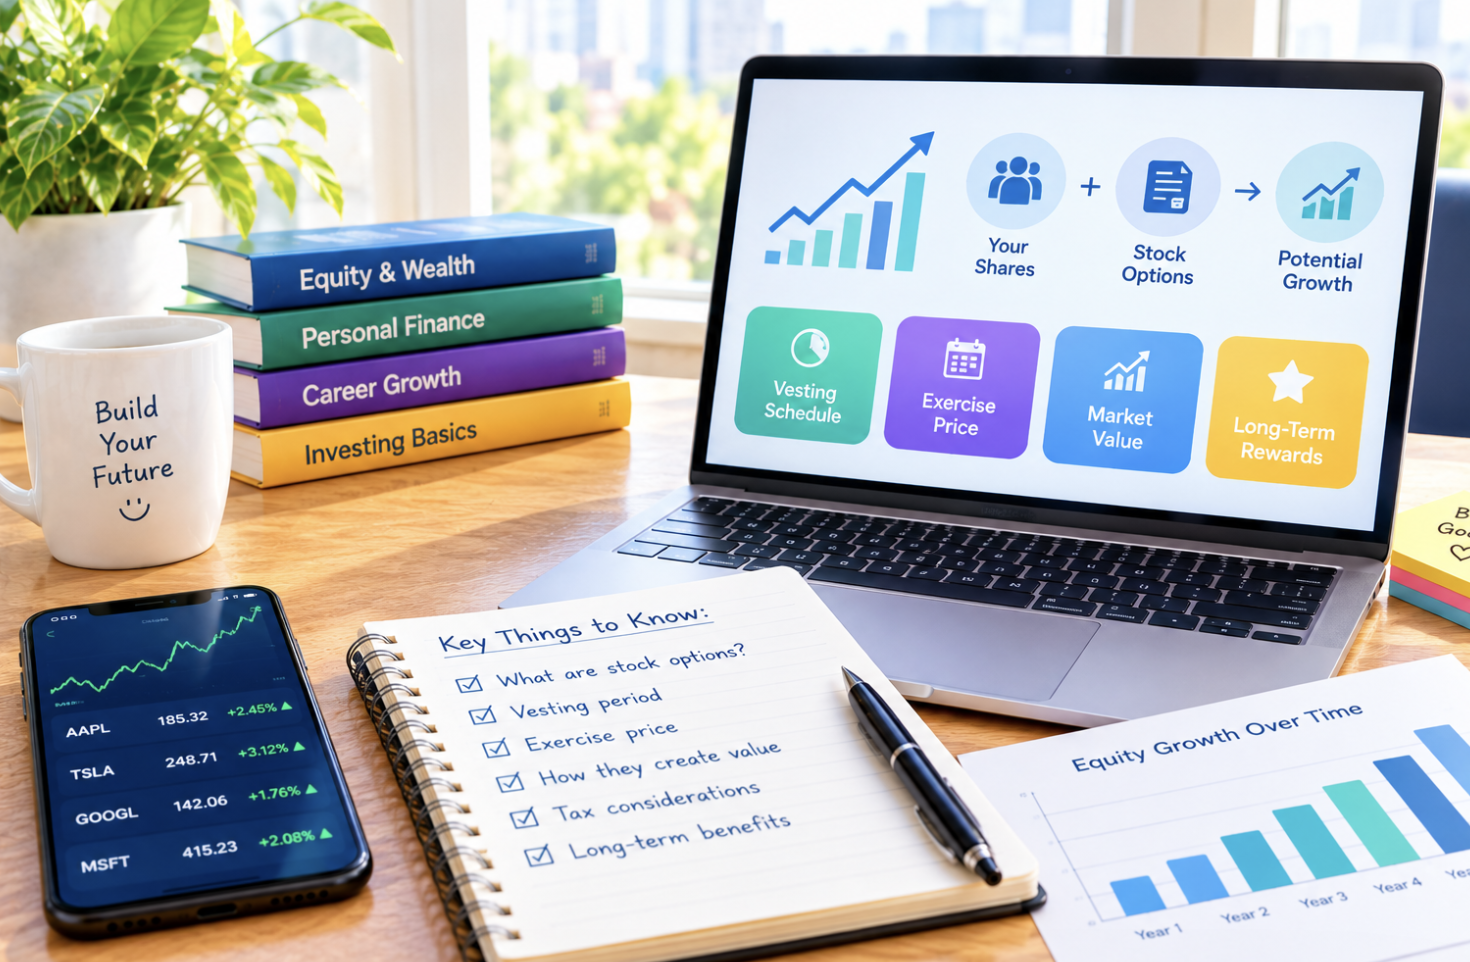
A stock option gives an employee the right, though not the obligation, to purchase a specific number of company shares at a predetermined price, called the strike price, within a defined window of time. The core value proposition depends entirely on the company’s share price rising above that strike price before the option expires, if the market price stays below the strike price, the option holds no financial value and typically isn’t worth exercising at all. This structure ties an employee’s potential financial upside directly to the company’s future performance, which is precisely the incentive alignment stock options are designed to create.
The Difference Between ISOs and NSOs
Employee stock options generally fall into two tax categories, and understanding which type you’ve been granted affects both strategy and tax consequences.
- Incentive stock options, or ISOs, offer potentially favorable tax treatment but come with stricter eligibility rules and holding requirements
- Non-qualified stock options, or NSOs, are taxed as ordinary income upon exercise but come with fewer restrictions on who can receive them
- ISOs are typically reserved for employees, while NSOs can be granted to contractors, advisors, and board members as well
- The specific tax treatment of ISOs depends on meeting holding period requirements that, if violated, convert the favorable treatment into ordinary NSO-like taxation
This distinction is worth confirming directly with your company’s equity documentation or a tax professional, since assuming the wrong category can lead to costly tax planning mistakes that only become apparent well after the relevant decisions have already been made.
How Vesting Schedules Work
Stock options rarely become available all at once, instead, they typically vest gradually according to a schedule outlined in the grant agreement.
- A common structure vests options over four years, with a one-year cliff before any options vest at all
- The cliff means leaving the company before the first anniversary typically forfeits the entire grant with nothing vested
- After the cliff, options often vest monthly or quarterly for the remainder of the vesting period
- Some companies have moved toward alternative vesting structures without a traditional cliff, though the four-year model remains widespread
Your specific vesting schedule matters enormously for career decisions, since leaving a company just before a vesting cliff or a major vesting milestone can mean forfeiting a substantial amount of unvested equity that would have vested with just a little more patience.
What It Means to Exercise an Option
Exercising an option means purchasing the shares at the strike price, converting the right to buy into actual ownership of company stock.
- Exercising requires paying the strike price multiplied by the number of options being exercised, an upfront cash cost
- Some companies offer cashless exercise programs that use a portion of the resulting shares to cover this cost
- Exercising triggers a tax event under most circumstances, even if the shares aren’t immediately sold afterward
- Waiting to exercise until closer to expiration reduces upfront cash needs but increases the risk of missing a favorable window entirely
This upfront cash requirement surprises many employees who assume options are simply free money that materializes automatically, when in practice exercising often requires a meaningful financial commitment well before any shares can be sold for cash.
The Tax Complexity Surrounding Stock Options
Taxation is where stock options become complicated, and getting this wrong can result in an unexpectedly large tax bill or a missed opportunity for more favorable treatment.
- The alternative minimum tax can apply to ISO exercises even when no shares have been sold yet, creating a tax bill without corresponding cash
- NSO exercises generate ordinary income tax immediately based on the difference between the strike price and current market value
- Selling shares after exercise triggers capital gains tax, with the specific rate depending on how long the shares were held
- State tax treatment of stock options varies, adding another layer of complexity for employees who’ve relocated during their vesting period
Given how much money can be at stake, consulting a tax professional experienced specifically with equity compensation before making exercise decisions is a worthwhile investment, even for employees who normally handle their own taxes without professional help.
Timing Considerations for Exercising and Selling
The decision of when to exercise options and when to sell the resulting shares involves balancing tax consequences, cash flow needs, and a bet on the company’s future performance.
- Exercising early, while the difference between strike price and market value is small, can minimize the eventual tax bill
- Waiting to exercise reduces upfront risk but can result in a much larger tax liability if the share price has risen substantially
- Selling immediately after exercise, sometimes called a same-day sale, avoids further market risk but often forgoes favorable long-term capital gains treatment
- Holding shares after exercise for the required period can qualify for lower capital gains rates but exposes the position to further market volatility
There’s no universally correct answer here, since the right approach depends on personal financial circumstances, risk tolerance, and conviction about the company’s prospects, which is exactly why this decision benefits from individualized professional guidance rather than a generic rule of thumb.
What Happens to Options When You Leave a Company
Departing a company, whether voluntarily or not, triggers specific rules about what happens to both vested and unvested options that every employee should understand well before any departure decision.
- Unvested options are typically forfeited entirely upon departure, regardless of the reason for leaving
- Vested options usually come with a limited post-termination exercise window, often 90 days, though this varies by company
- Missing this exercise window typically forfeits the vested options entirely, even though they had already vested
- Some companies have extended these windows in recent years, responding to criticism that short windows unfairly penalized departing employees
Checking your specific post-termination exercise window before making any career decision involving a company where you hold options is a critical step that far too many employees skip, sometimes at significant financial cost.
How Company Size and Stage Affect Equity Value
The stage of a company at the time options are granted plays a major role in how much risk and potential reward that equity carries, a factor employees sometimes overlook when comparing offers from different companies.
- Early-stage private companies offer options with high potential upside but a real chance of ending up worthless
- Later-stage private companies closer to a public offering or acquisition carry somewhat lower risk but also lower potential multiplier
- Public company grants offer more predictable, liquid value since shares can typically be sold immediately after vesting
- Comparing a strike price against a company’s most recent valuation round gives a rough sense of how much room for growth remains
Employees evaluating a job offer with equity should ask directly about the company’s most recent valuation and funding stage, since this context matters as much as the raw number of options offered when judging what that grant might realistically be worth.
Common Mistakes Employees Make With Their Equity
Beyond missing exercise windows, several other recurring mistakes cause employees to get less value from their equity than they otherwise could have.
- Not tracking vesting dates closely enough to time a departure decision around an upcoming vesting milestone
- Failing to model the tax impact of a large exercise before doing it, resulting in an unexpected bill
- Ignoring the company’s specific plan documents in favor of general advice that doesn’t account for that company’s particular rules
- Treating equity as guaranteed compensation rather than an uncertain bet tied to company performance
Avoiding these mistakes usually requires nothing more than reading the actual plan documents carefully and asking direct questions of a company’s equity administrator or a tax professional before making irreversible decisions.
How Startups Structure Equity Differently Than Larger Companies
Equity compensation structures vary between early-stage startups and larger, more established companies, and these differences helps set realistic expectations when comparing offers.
- Startups often grant a larger percentage of total company ownership but with correspondingly higher risk of the company failing entirely
- Larger companies typically grant smaller percentage stakes but with a much higher likelihood the equity retains real value
- Startup strike prices are usually much lower in absolute dollar terms, reflecting the company’s lower valuation at that stage
- Refresh grants, additional equity issued to existing employees over time, are more standardized at larger companies than at early-stage startups
Comparing equity offers across companies at different stages requires looking past the raw number of shares or options offered toward the actual percentage ownership and realistic probability of that equity eventually becoming valuable.
Questions Worth Asking Before Accepting an Equity-Heavy Offer
Employees considering a job offer weighted heavily toward equity compensation benefit from asking a specific set of questions before accepting, rather than assuming the number on an offer letter tells the full story.
- What percentage of the fully diluted company does this grant represent, not just the number of shares
- What was the company’s most recent funding round valuation, and how has it changed since then
- What is the standard vesting schedule, and does it include a cliff before any equity becomes available
- What is the post-termination exercise window, and has the company ever extended it for departing employees
Asking these questions directly during salary negotiations, rather than after accepting an offer, gives a much clearer picture of what the equity portion of a compensation package is worth relative to a straightforward cash salary.
How Equity Compensation Differs Across Industries
The structure and generosity of equity compensation varies across industries, reflecting different norms around cash versus equity trade-offs in total compensation packages.
- Technology companies have historically relied more heavily on equity as a significant portion of total compensation
- More traditional industries often offer smaller equity components, relying more heavily on cash salary and bonuses
- Industry-specific equity norms affect how competitive a specific offer looks compared to others in the same field
- Typical equity practices within your specific industry provides useful context for evaluating any individual offer
Researching typical equity practices within a specific industry, rather than comparing offers purely against unrelated fields, produces a far more accurate sense of whether a given equity package is competitive.
How Divorce and Estate Planning Intersect With Stock Options
Equity compensation introduces specific complications in both divorce proceedings and estate planning that many people don’t anticipate until directly confronted with them.
- Unvested options earned during a marriage may be considered marital property subject to division in some jurisdictions
- Valuing private company equity for legal purposes is notoriously difficult given the absence of a public market price
- Estate plans need specific provisions addressing what happens to unexercised options if the holder passes away unexpectedly
- Consulting both a family law attorney and a tax professional is worth the cost when equity represents a meaningful share of overall assets
Equity in Remote and International Roles
Employees working remotely for a company based in another country should pay close attention to how that country’s specific tax treaties and equity regulations apply to their grant, since standard domestic guidance often doesn’t directly address the added complexity international remote arrangements introduce.
How Secondary Markets Let Employees Access Liquidity Before an Exit
Some employees at private companies now have the option to sell a portion of their vested shares through a secondary market before the company goes public or gets acquired, providing a way to access some value without waiting years for a formal exit event. These transactions typically require company approval and often come with restrictions on price and buyer eligibility. This option has grown more common at well-established private companies specifically because it helps retain employees who might otherwise leave for the liquidity a public company job would offer instead.
Final Thoughts
Stock options can represent a significant part of total compensation, but only for employees who understand the vesting schedule, tax implications, and exercise deadlines well enough to capture that value rather than letting it quietly expire. Taking the time to read your specific grant agreement carefully, and consulting a tax professional before making major exercise decisions, turns what can feel like confusing paperwork into one of the more valuable pieces of your overall compensation.
Frequently Asked Questions
What happens to my stock options if the company gets acquired?
This depends on the specific acquisition terms and your existing option agreement. Options might be converted into equivalent equity in the acquiring company, cashed out at a value determined by the deal terms, or accelerated to fully vest immediately, depending on provisions negotiated as part of the acquisition agreement.
Can I lose money by exercising stock options?
Yes, if you exercise and then the share price declines below your strike price, or if you owe taxes on the exercise that exceed what you can recover by eventually selling the shares. This is part of why timing and tax planning matter so much when deciding whether and when to exercise.
How do I find out my specific vesting schedule and strike price?
This information should be documented in your original grant agreement, typically provided by your company’s HR or equity administration platform. If you can’t locate these documents, your company’s equity or HR team should be able to provide the specific terms of your grant directly.
Is it better to take a lower salary in exchange for more stock options?
This depends heavily on your personal risk tolerance, financial situation, and belief in the company’s prospects. Stock options carry real risk of ending up worthless, so this trade-off works better for people who can afford that downside risk and have real conviction about the company’s future.
Do stock options expire if I don’t exercise them?
Yes, options typically come with an expiration date, often ten years from the grant date for employees who remain with the company, though this shortens upon departure as discussed earlier. Letting options expire unexercised means losing their value entirely, even if they would have been profitable to exercise.
Should I diversify by selling company stock soon after exercising?
Many financial advisors recommend diversifying out of concentrated single-company stock positions, including shares from exercised options, to reduce risk tied to any single company’s performance. The right approach depends on your overall financial picture, though holding too much of your net worth in one company’s stock is a commonly cited risk worth addressing deliberately rather than by default.