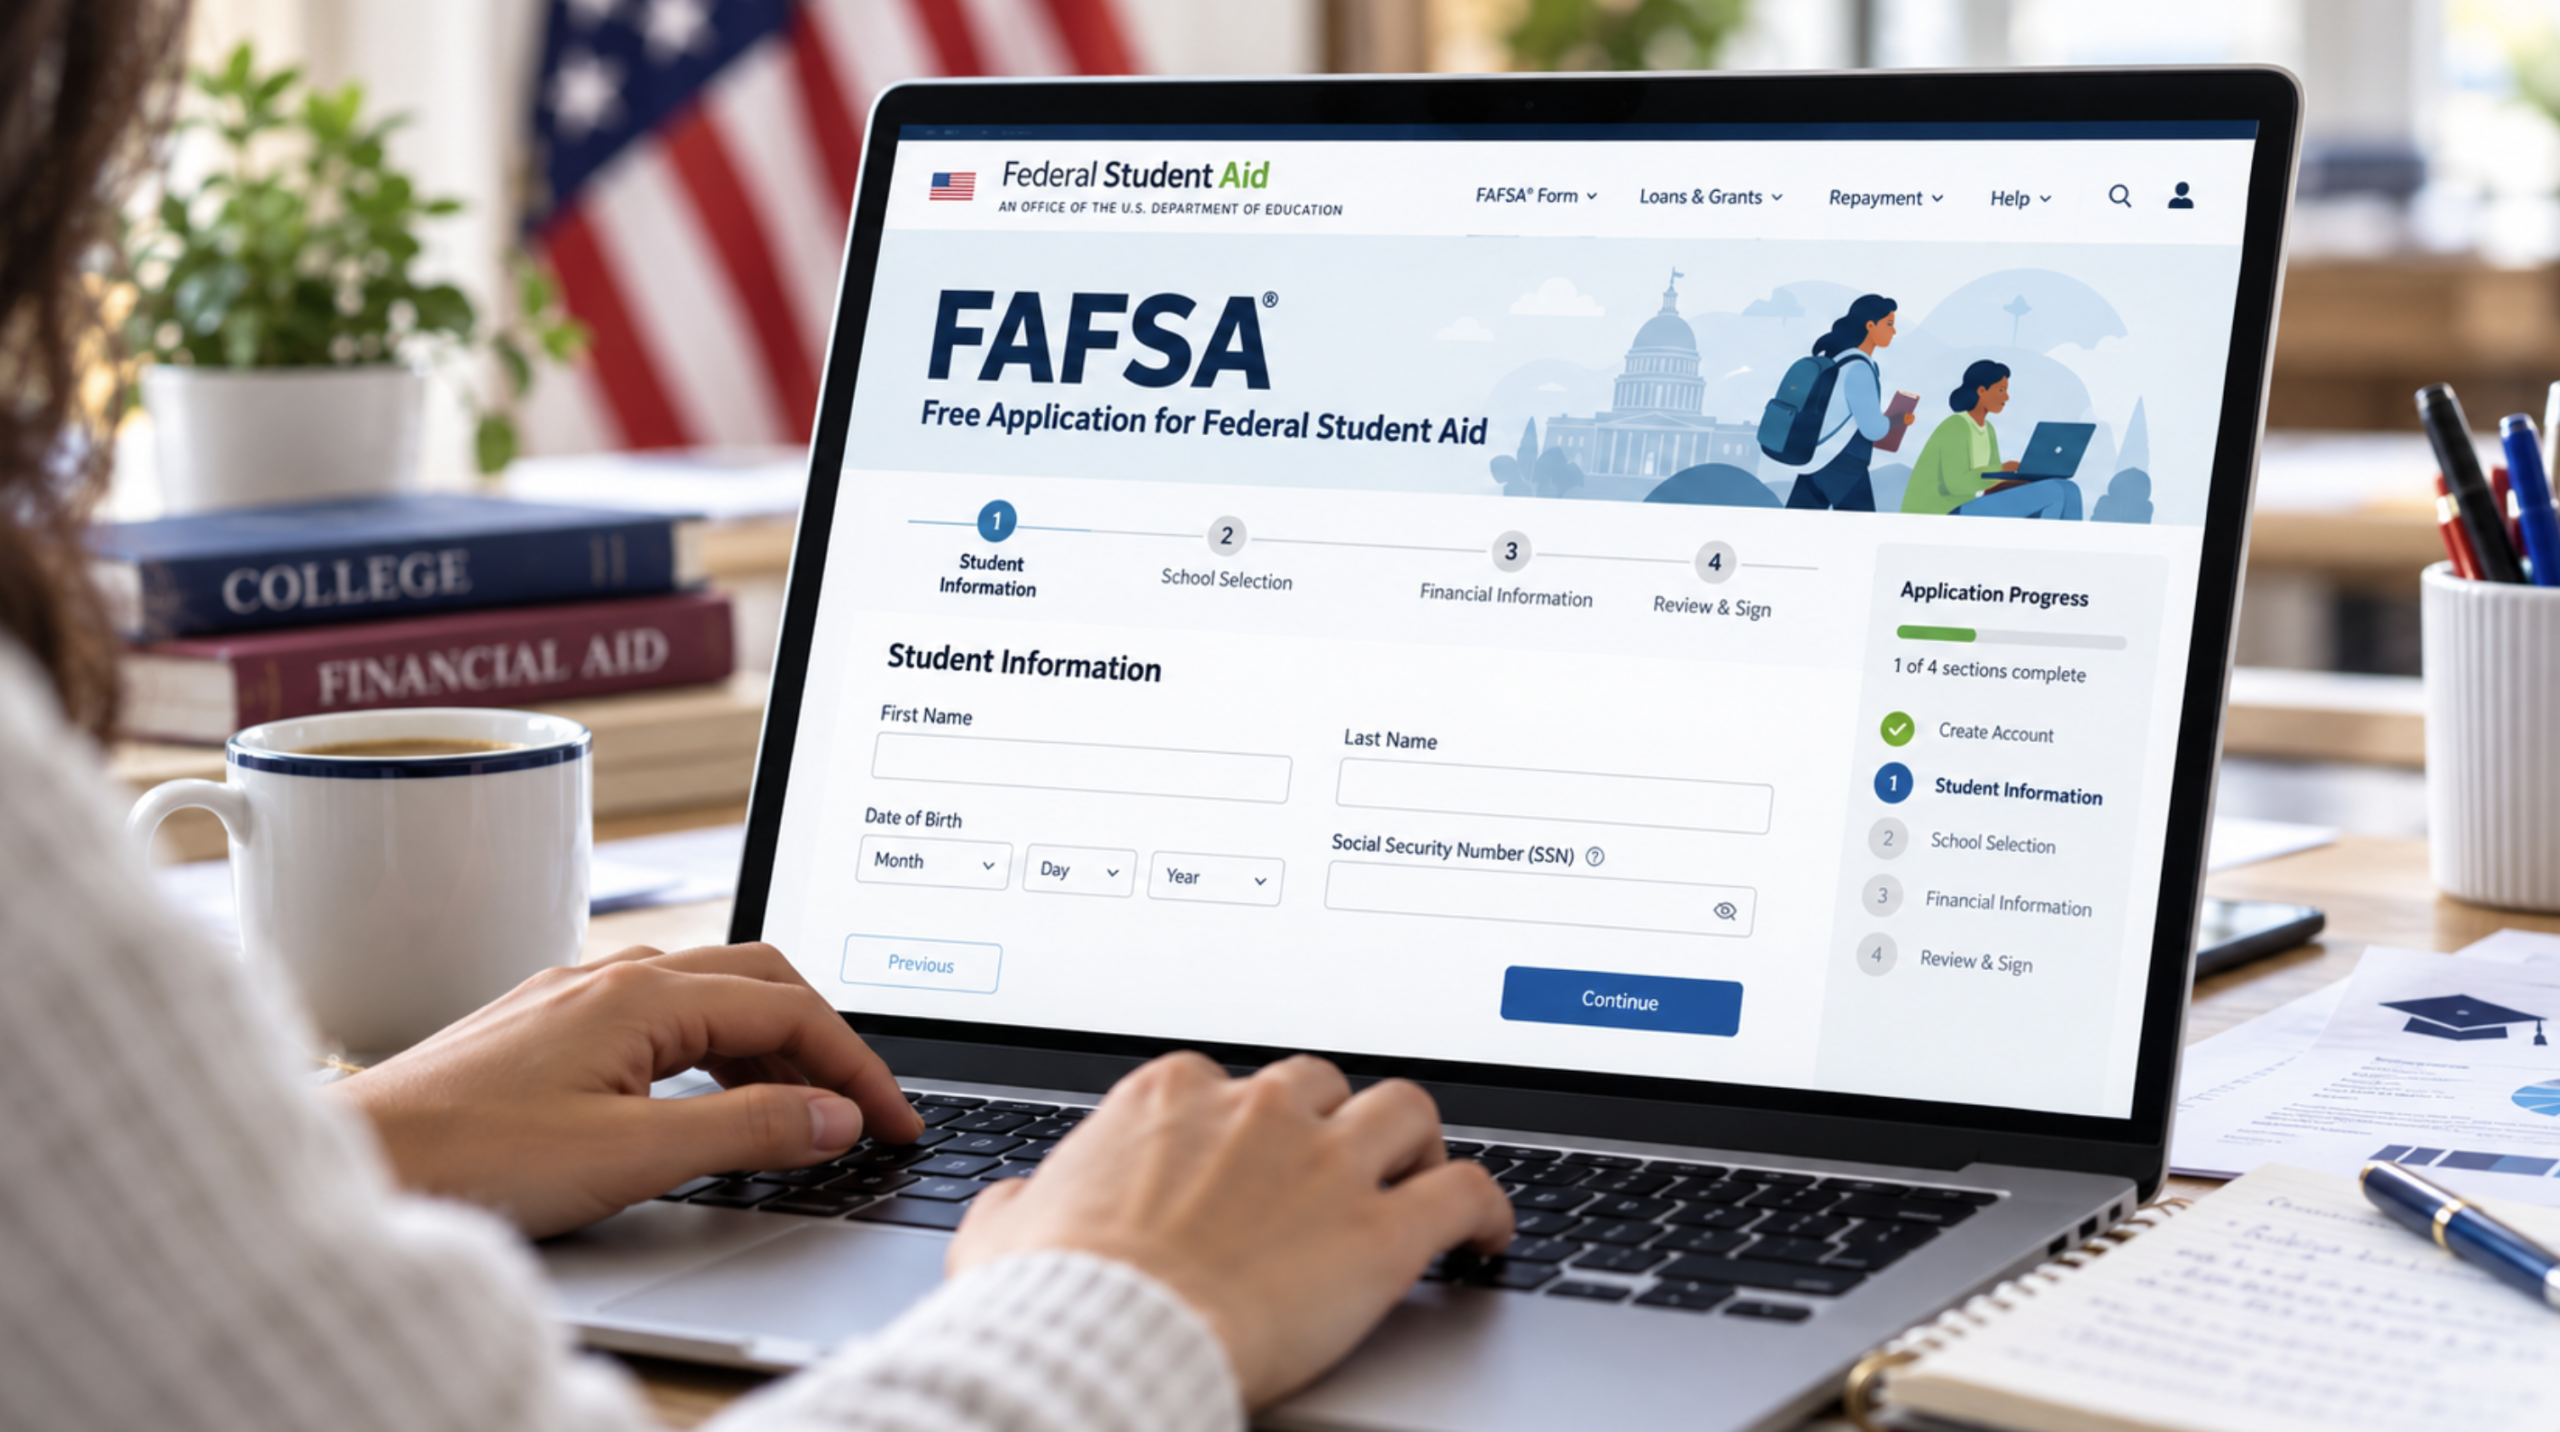
The Free Application for Federal Student Aid is the gateway to most grants, loans and work-study jobs in the United States, so the date it opens shapes how calmly a family can plan for college costs. This year the Education Department opened the 2027-28 form ahead of the traditional October start and reworked how it functions.
In this article we will explore what changed, which documents and accounts to prepare, how deadlines work, and a practical order of steps.
An Early Opening for the Second Year Running
The Education Department put the 2027-28 form online at StudentAid.gov in late September, according to a report from The National News Desk carried by WJLA on 24 September 2026. The form is meant for students who begin classes on or after 1 July 2027, which covers the high school seniors applying this fall as well as current college students planning their next year.
Federal law requires the department to make the application available by 1 October, so opening before that date is a bonus rather than a legal requirement. It is also the second year in a row that the form has come out ahead of the old schedule. For readers who remember the older rhythm, the change in timing is bigger than it sounds.
For decades the form opened on 1 January, which left families scrambling in the winter to gather tax paperwork while colleges waited for data before they could write award letters. Moving the opening to the fall gives families several extra months to work, and it gives schools a longer runway to review the information they receive. Whether that translates into smoother award letters is something each college will decide for itself, but the calendar now clearly favors people who start early.
Who the Form Is For
Almost every student who hopes to receive money from the federal government, a state or a college should file. That includes first-year students, transfer students and returning students, and it includes families who assume they earn too much. Many colleges use the same form to decide on their own scholarships, and several state programs require it as well.
Eligibility for any particular program depends on rules that the department and each school publish, and this article does not list income cutoffs or award sizes because those details change and sit outside the verified news.
Why the Early Start Matters in Practice
The practical value of an early opening is time. A family that files in the first weeks has room to fix a mistake, locate a missing document, or wait for a parent who travels for work to sign in. It also means the student can see offers sooner and compare them while there is still time to visit campuses or ask a financial aid office a question.
None of this requires rushing, and families who need more time still have months in which to apply. It simply removes an excuse for putting the task off until a deadline is looming.
The Changes Families Will Notice
The department and press coverage of the launch describe a form that has been reworked in several visible ways. According to The National News Desk, the changes include clearer language, a simpler renewal process, the ability to invite contributors such as parents or spouses by text or email, a view of potential earnings outcomes for schools an applicant is considering, and a fraud-detection system.
A department notice reviewed earlier in the year added that data for returning students would be pre-populated and that parents with several children could reuse their information. Each of these changes solves a problem that families have complained about for years.
Plainer Wording and a Simpler Renewal
Anyone who has stared at a financial form and wondered what a question was really asking will appreciate clearer language. The department says the rewrite is meant to cut confusion, and confusion is the leading cause of abandoned or incorrect applications. Renewal is the other half of the story.
Students who filed last year should find that much of what they entered is already there, which turns a full application into a review exercise. The sensible habit is still to read each pre-filled answer, because a family situation can change in a year even when a database has not caught up.
Inviting Contributors by Text or Email
A dependent student usually needs a parent to supply financial information, and a married student needs a spouse. In the old process that handoff could be clumsy, with logins shared over the phone or on sticky notes. The new approach lets the applicant send an invitation to each contributor by text message or email, and the contributor then adds their own information in their own account.
This is better for privacy, because nobody has to type another person’s secrets, and it is better for security, because credentials stay with their owner. It does mean you should tell the people you are inviting to expect the message, so it is not mistaken for spam.
Parents With Several Children
The department’s earlier notice said parents with more than one child could reuse their information. For a household with two or three students applying in different years or in the same year, this is a real saving, because the most laborious part of the form is usually the parent section.
Reuse still leaves each student responsible for their own application, so every child needs to submit and every school list needs to be entered separately. The time saved is on data entry, not on thinking about which schools to include.
Earnings Outcomes and Fraud Detection
Applicants can now see potential earnings outcomes for the schools they are considering. This is useful context, but treat it as one input among many. Earnings figures for a program describe past graduates, not a promise for the next one, and they cannot capture a student’s own goals, location or field.
The fraud-detection system is described only in broad terms in the coverage, so readers should not expect a detailed account of what it checks. Its purpose is presumably to stop identity theft and fake applications. For families the lesson is to supply accurate information and to respond quickly if the department asks for verification.
Fifteen Minutes and What to Make of the Claim
The department says some families can finish the form in about 15 minutes. Nicholas Kent, the Under Secretary for Higher Education, put it more strongly, saying the form “takes 15 minutes on average,” compared with “hours or even days” previously. Those are official statements and should be read that way: the average depends on who files, and it is most likely to hold for families with simple finances, returning students whose data is pre-filled, and contributors who respond promptly.
A fair way to think about it is that the typing may take 15 minutes but the preparation does not. Locating a tax return, confirming a bank balance, or waiting for a divorced parent to log in can stretch a quick session into a week. The speed claim is plausible for a family that has its documents together, and it is a good reason to do that preparation first. Treat 15 minutes as the length of the final sitting, not the length of the project.
Kent also framed the goal in simple terms: “We don’t want students leaving money on the table.” Education Secretary Linda McMahon said the launch “ensures American students and families have access to the critical resources they need.” Those remarks reflect a long-standing concern in higher education, which is that many students who would qualify for help never file. The reasons range from not knowing about the form to fearing it is too hard. A shorter, clearer form addresses the second reason, though the first still depends on parents, counselors and teachers spreading the word.
What the Form Unlocks
Filing the form does not by itself pay for anything. It is the application that lets the federal government, states and schools decide what help to offer. In general terms it opens the door to federal grants such as Pell Grants, to federal work-study, and to federal student loans.
Many states and colleges also use the information to decide on their own aid, which is why a family with no expectation of federal help may still benefit. The form is free to complete, and that point deserves repeating because paid imitators exist.
The table below summarizes the main kinds of help and what they generally mean. It is a general guide, and the amounts, eligibility rules and terms are set by the department, the states and each school.
| Type of help | In general terms | Who decides |
| Federal grants such as Pell Grants | Money that does not have to be repaid, based on financial need | Federal rules, applied by the school |
| Federal work-study | Part-time jobs for eligible students to help cover costs | The school, from limited funds |
| Federal student loans | Borrowed money that must be repaid, often with some protections | Federal rules, offered by the school |
| State aid | Grants or scholarships from a student’s home state, often tied to filing the form | State agencies, with their own deadlines |
| College aid | Scholarships and grants that a school offers from its own budget | Each college’s financial aid office |
Two notes about this table. First, the word limited matters, because some programs run out of money. Federal grants are not rationed in the same way as some campus funds, but work-study and certain state and college awards can be exhausted, which is why timing is not trivial. Second, loans appear in a financial aid offer alongside free money, and they are not the same thing.
A good habit is to separate the offer into money you keep and money you must repay before comparing schools. One more point about the table is that the help on offer is layered. A student might receive a federal grant, a state scholarship, a college grant and a loan all in the same award letter, each governed by a different rulebook and each with its own conditions for renewal.
Keeping the layers straight matters, because a condition such as a minimum course load or a grade requirement can end an award that a family assumed would continue. Read the fine print on every line, and ask the aid office what must be maintained from one year to the next.
Accounts and Documents to Prepare
A smooth session depends on two kinds of preparation: accounts and records. Neither is hard, but both can create delays when handled at the last minute. The department’s site is the place to begin, and it is worth typing the address yourself rather than following a link in an email or an advertisement.
Accounts for the Student and Each Contributor
The student needs a StudentAid.gov account with an FSA ID, and every contributor, whether a parent or a spouse, needs one too. Because the new process sends invitations by text or email, each person should be ready to receive a message and create or sign in to their own account.
Set these up early, since identity checks can take time. An FSA ID works like a signature on federal documents, so keep it private. Never share it with a school employee, a tutor, a paid service or a friend, and use a unique password stored in a password manager. If a website asks you to hand over your FSA ID so someone can do the form for you, close the page.
Records to Gather
The form typically asks for tax information, records of assets and identification numbers such as Social Security numbers for the student and contributors.
Gather the tax return or returns the form asks about, recent bank and investment statements, and details on any untaxed income if the form requests it. The tax year the form refers to has varied in the past, so read the on-screen instructions rather than assuming.
If a contributor is not a citizen or does not have a Social Security number, the form has separate guidance, and a school aid office can explain the options without judgment. A checklist helps because the mistakes people make are usually small ones. The table below lists what to collect and why.
| Item | Why it is needed | Tip |
| Student identification numbers | To link the form to the student’s records | Make sure names match official documents |
| Contributor identification numbers | To let each contributor add their own data | Confirm each person’s email or mobile number |
| Tax information | To report income | Use the tax year the form specifies |
| Records of assets | To report savings, investments and other holdings | Have current statements ready |
| List of schools | To send results to each college | Add every school you are considering |
| FSA ID credentials | To sign in and sign the form | Store them securely and never share them |
Deadlines, Offers and What Comes After Filing
Calendars That Do Not Match
The coverage of the launch lists no filing deadline, and that silence is a reminder that there are several clocks running at once. The federal government has its own cutoff for each award year, which the department publishes. States set their own dates, and some of them are earlier than the federal date and are enforced strictly.
Colleges add their own priority dates, often tied to when they hand out limited institutional money. A family that watches only the federal date can miss a state or school date that matters more. Because of this, the safest plan is to treat the earliest date among your schools and your state as your deadline.
Check each college’s financial aid page or call its office, and look up your state agency’s schedule. Students applying to a mix of public and private schools often discover that the private colleges ask for additional forms with their own dates. Write all of them on one calendar so nothing is a surprise.
Filing early also has a practical advantage beyond meeting dates. If a mistake is found, there is time to correct it, and if the school asks for verification documents, there is time to send them before an aid package is built.
The department said colleges now get more time to review aid information, which should help schools process what they receive, but it does not mean every school will issue offers early. Ask each aid office when you can expect your offer so you can plan around it.
Confirming and Following Up
Submitting is the middle of the process, not the end. The student and contributors will see a confirmation, and each college you listed receives the information. Review the confirmation for errors, and keep a record of it.
Colleges may then ask for supporting documents, especially when the data looks inconsistent or the application is selected for verification. Respond quickly and keep copies of what you send.
Comparing Offers When They Arrive
Award letters are not standardized, and two schools can describe similar packages in very different ways. Sort every line into one of three piles: money you keep, such as grants and scholarships; money you earn, such as work-study; and money you must repay, such as loans.
Then subtract the first pile from the full cost of attendance at each school, including housing, food, books and transportation, not only tuition.
The result is the figure that matters, and it can make a school with a higher sticker price cheaper than a school with a lower one. If an offer is unclear, ask the aid office to explain each line in writing, and do not be shy about asking whether a particular award renews in later years.
Reading the Student Aid Index
The form produces a number known as the Student Aid Index, which schools use as a starting point in estimating how much a family can contribute. It is an index, not a bill and not a prediction of what a college will charge. Two families with the same figure may receive very different offers because schools have different prices and different budgets.
If your number surprises you, check your inputs first, and then talk to the financial aid office about whether any part of your situation is not reflected.
Appeals and Special Circumstances
The form reflects a snapshot, and life does not always fit a snapshot. A job loss, a medical emergency, a death in the family or a large unexpected expense can make the data on the form misleading. Colleges have processes for special circumstances and appeals, and a student can ask the aid office to take a second look.
Expect to provide documentation, and expect the answer to vary by school. The best time to ask is as soon as the circumstance occurs, not after the semester has started.
Scams and Paid Help
Because the form is free, anyone charging for it is selling something the government gives away. Some companies run websites that look official and ask for payment or for your FSA ID. Others promise to guarantee scholarships. A trustworthy source never asks you to pay to file, and legitimate help from a school counselor, a nonprofit advising program or a college aid office is free.
The department’s fraud-detection system is one safeguard, but the stronger one is a family that knows the form costs nothing and keeps its credentials to itself.
Steps in a Sensible Order
Families can turn all this into a calm sequence. The order below assumes a student is applying for the first time, but a returning student can skip the early items.
Step One: Set up Accounts and Talk to Your Contributors
Create the student account and FSA ID first, then tell each parent or spouse who will be asked to contribute. Ask them to set up their accounts and to watch for the invitation by text or email. This step has the longest lead time, because people forget passwords and miss messages.
If a parent is out of the country, has a different last name, or lives apart from the student, work out in advance who counts as the contributor and ask the school aid office if the situation is unclear.
Step Two: Collect Documents and Build Your School List
Gather tax records, asset statements and identification numbers in one folder, paper or digital. Decide which colleges you want to receive the data, including backup choices, and look up each school’s priority date and your state’s date.
Use the earnings outcome information to compare programs, and keep in mind what it can and cannot tell you.
Step Three: File, Review and Keep Records
Sit down with the contributors, complete the form, review every answer, and submit. Save the confirmation, and put any follow-up requests from colleges on a calendar. When offers arrive, separate grants from loans and from work-study, and compare the net cost at each school rather than the sticker price.
Step Four: Renew Every Year
Aid is not a one-time event. Students who stay in college must file again, and the simpler renewal process should make that easier. Treat renewal as a yearly habit that takes place in the fall, and keep your account credentials secure between sessions.
This article is general information, not financial or legal advice. Rules, forms and deadlines can change, so confirm details with the Education Department, your state agency and each college’s financial aid office before you act.
Frequently Asked Questions
When Did the 2027-28 FAFSA Open?
The Education Department opened it in late September 2026, according to a report dated 24 September. That was ahead of the 1 October date the law requires, and the second year in a row the form has opened early.
Who Should Fill Out the 2027-28 Form?
It is for students who plan to start classes on or after 1 July 2027. Nearly anyone who wants federal, state or college aid should file, since many schools and states use it to decide on their own awards.
How Long Does the FAFSA Take to Complete?
The department says some families can finish in about 15 minutes, and Under Secretary Nicholas Kent said the form “takes 15 minutes on average.” Your own time depends on how ready your documents and contributors are.
Does the FAFSA Cost Anything to Submit?
No. The application is free, and you should be wary of any website or person who asks for payment or for your FSA ID. Help from a school counselor or college aid office is also free.
Can Parents and Spouses Be Invited to the Form by Text or Email?
Yes, according to coverage of the launch, applicants can invite contributors such as parents or spouses by text message or email. Each contributor then signs in to their own account to add their information.
Is There a Federal Deadline for the 2027-28 Form?
The launch coverage listed no filing deadline, so check the department’s site for the date. State and college deadlines may fall earlier, so use the earliest one that applies to you.